With the Budget approaching, some buyers and sellers may be waiting for greater certainty before committing to a move. While any measures announced may help boost confidence, there are practical steps people can take now to prepare and avoid unnecessary delays when the time comes.
A healthy housing market needs movement at every level. The property market relies on people being willing and able to move at different stages of their lives.
First-time buyers need properties to become available at the bottom of the market, and that often depends on existing homeowners feeling confident enough to move up the ladder into a larger home. Equally, those looking to downsize need to feel comfortable taking that next step.
One of the most important things buyers can do to keep things moving is to get their finances and supporting documents in order before a transaction begins.
Anti-Money Laundering (AML) requirements are an essential part of the conveyancing process, but they can become complicated, particularly where deposits have been built up over many years, include gifts from family members or involve money moving between different accounts.
In some cases, tracing the source of a deposit can take considerable time. Conveyancers need to understand where the money has come from and follow its journey, which means missing bank statements or other supporting documents can hold things up.
Early engagement with clients can help identify potential issues before they become obstacles to a transaction. Encouraging buyers to provide bank statements and evidence of the growth of their deposit at the outset, particularly where funds have been gifted or transferred between accounts, can help avoid delays in satisfying AML requirements.
For sellers, reviewing title documentation early can help flag issues before a buyer is ready to proceed. Clear communication about the process, likely timescales and the information required from clients can also help manage expectations and keep transactions on track.
Leasehold properties can present additional challenges.
Obtaining the necessary management information from a freeholder or managing agent can add significant time to a transaction. The Conveyancing Association has reported that it takes an average of 54 days from payment to obtain LPE1 and FME1 leasehold management information. While sellers may not be able to control how quickly that information is supplied, asking about the process early and making the necessary arrangements can help avoid adding to the delay.
More generally, clear communication between everyone involved in a transaction is important.
Buyers and sellers should respond promptly to requests for information, raise questions as soon as they arise and make sure they understand what is needed from them at each stage.
There is no single reason why property transactions are delayed and, in some instances, fall through. Economic uncertainty, the time of year, complex legal issues, third party involvement and the availability of information can all play a part.
Whilst the use of AI within transactions is considered by some to help, caution should be applied by all who rely on AI to ensure enquiries which are generated are checked thoroughly and cross referenced against the title documents provided.
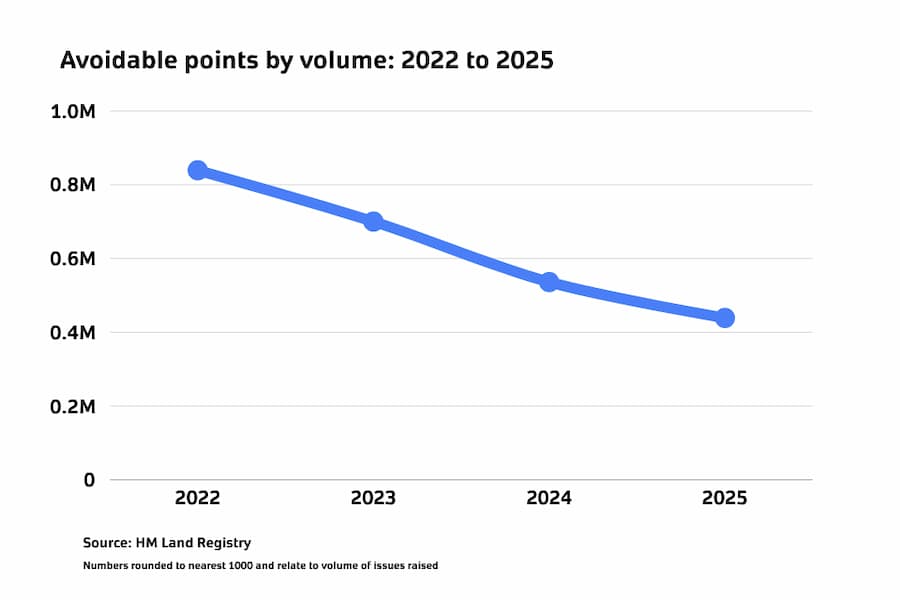
Receiving 50 plus enquiries on any property will inevitably slow the process down especially where a large number of those enquiries do not apply. Being informed and prepared can help reduce the risk of hold-ups and make the process less stressful for everyone involved.
Whether there are changes announced in the Budget, or not, my advice is simple: encourage clients to start preparing early, gather the necessary paperwork and contact an experienced conveyancer early, before a property is marketed for sale. While not every aspect of a property transaction is within their control, helping clients understand what is needed and when can reduce delays and put them in a stronger position to move when the right opportunity arises.
About the author
 Emma has worked within a residential conveyancing team since 1999 and qualified as a Chartered Legal Executive in 2011. She deals with a wide range of property transactions, including freehold and leasehold sales and purchases, transfer of equity, remortgages, sales of part, help to buy schemes, new build properties and shared ownership. Emma also deals with matters of a complex nature including equity release schemes, adverse possession claims and reconstitution of titles. Emma is also deputy Money Laundering officer providing guidance and assistance to the team to ensure that they remain complaint with the ever changing rules and practices.
The views expressed in this article are those of the author and not necessarily those of Today’s Conveyancer.