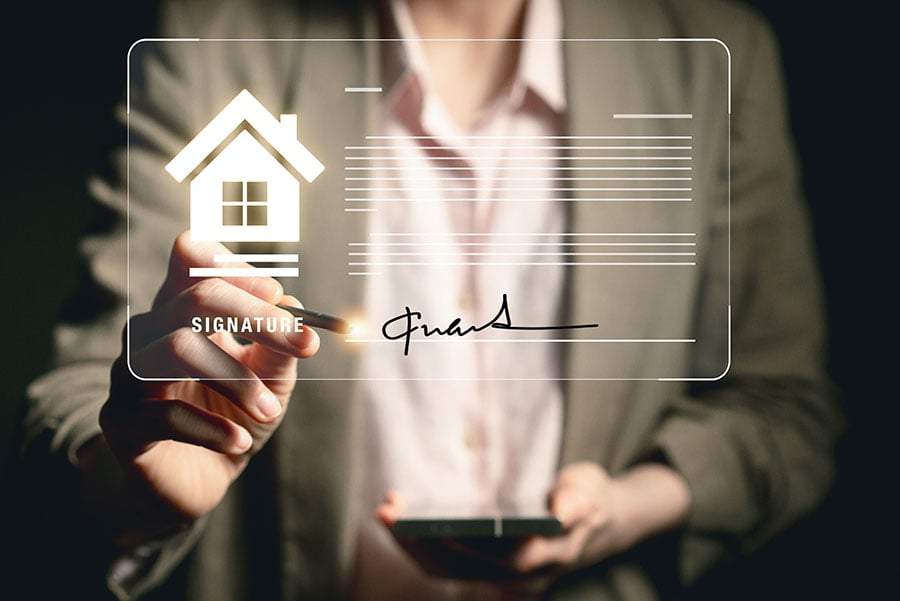
The use of Qualified Electronic Signatures (QES) at HM Land Registry has “rocketed” in the latest quarter, new research suggests, with 643 applications containing QES compared with one in the same period the previous year.
Despite a slow start to the adoption of e-signatures, HMLR data collected by mortgage and home buying consultants Novus Strategy showed in the most recent quarter (Q3) the number of applications that included QES at Land Registry has increased by 1,069%.
A key component in the digitisation of home buying and selling reforms, QES along with Smart Data and digital ID are helping to speed up transactions and reduce delays in conveyancing, said transformation and strategy partner at Novus, Chris Williams. He added wider adoption showed that Horizontal Digital Integration (HDI) is “gathering pace.”
“We know how important QES are to lenders and other businesses in homebuying because we had someone from a major building society explicitly address this on stage at a Novus event last month,” Williams explained. “We knew this to be the case and have been tracking the growth in these numbers since the very beginning.”
In the first quarter, five Land Registry applications contained QES, as opposed to 643 in Q3, a Freedom of Information request revealed.
It showed in total 706 applications had included them, 91.1% of them arriving in the latest quarter.
In February, Nationwide announced it was the first lender to allow mortgage deeds to be signed digitally and in October, conveyancing services provider LMS also rolled out QES for mortgage deed signing for lender and law firm customers.
Slow adoption pre-Q3 was part of the “configuration conundrum”, Novus stated, as different aspects of HDI needed to move in unison.
Williams concluded: “The momentum is certainly building now and it’s very exciting because it indicates that there’s much more going on behind the scenes, as lenders and others involved in homebuying build interoperability into the entire homebuying journey. For lenders, this starts with redesigning the mortgage journey but every actor in a transaction has an important part to play.”