A week before the government is set to unveil its ‘Your First Home’ scheme for first-time buyers, analysis of the previous government’s ‘Help to Buy’ scheme suggests it inflated new-build prices and helped stagnate the market.
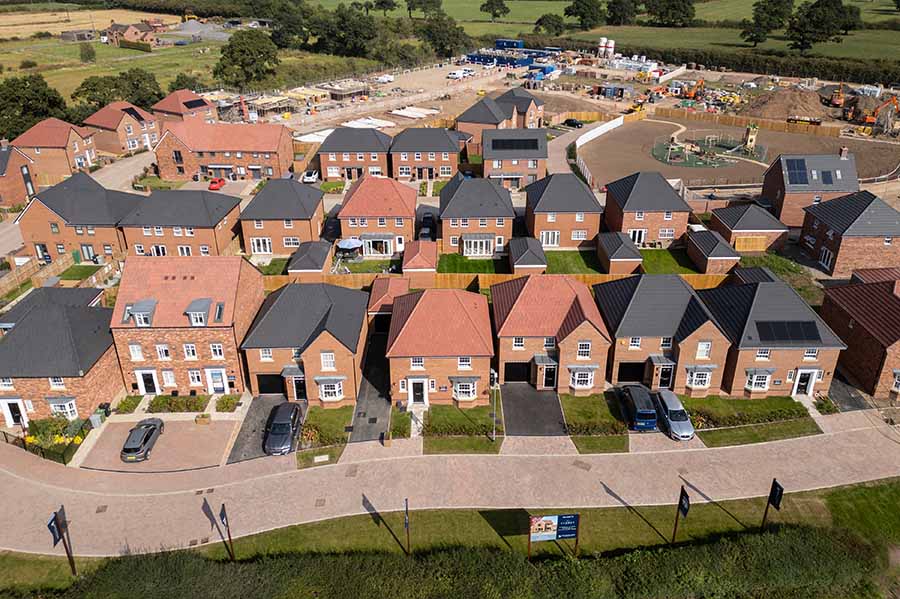
Help to Buy, which offered first-time buyers government-backed equity loans on new-builds, inflated new-build prices by 70.1%, according to new research from SAM Conveyancing.
More than 387,000 properties were purchased using the Help to Buy equity loan between April 2013 and March 2023.
During this period, housing delivery stagnated at an average of 152,791 completions per year, well below the 2007 peak of 223,590.
While Help to Buy assisted roughly 11% of all first-time buyers during that decade, it simultaneously created a captive market, accounting for between 35% and 50% of private new-build sales for major commercial housebuilders, SAM Conveyancing warns.
It is urging Prime Minister Andy Burnham and Chancellor John Healey to open the incoming Your New Home – a 2.5% deposit with equity loan scheme, the first government-backed help for first-time buyers since Help to Buy lapsed – to existing properties, and not only new-builds, in the 28th October Autumn Budget.
Andrew Boast, CEO of SAM Conveyancing, said: “Help to Buy was presented as a cure for Britain’s housing crisis, but the data proves it functioned primarily as a price-support mechanism for volume housebuilders.
He added: “Repeating this policy by restricting the incoming ‘Your First Home’ scheme solely to new developments will not magically double our construction capacity overnight.
“It will simply pump billions in state support into developer balance sheets, leaving buyers to absorb an immediate 40% price premium alongside unresolved leasehold costs and tight 28-day exchange ultimatums.”
SAM Conveyancing says throughout the decade where Help to Buy was in place, buyers paid an average new-build premium of 28.1%, with peaks reaching 37.8%.
In May 2026, the average new-build cost an average of £396,889 compared to £283,194 for existing housing stock.
“Britain does not just have a shortage of new houses; the entire property ladder is completely seized up. Pumping public cash exclusively into brand-new estates lines the pockets of big building firms, while everyday sellers who bought starter homes years ago are left stranded,” Boast added.
“If Chancellor John Healey genuinely wants to get Britain moving, he should let first-time buyers use this scheme on any property they choose. Backing purchases with independent professional valuations gives buyers real freedom, cuts out the developer red tape, and finally unfreezes the chains so first-time buyers can move in, and young families can move into their next home.”