
What property data, regional SMEs and today’s rate decision reveal about UK economic resilience.
As we limp through mid-September 2026, the UK economy has finally graduated from 2025’s “lacklustre” to 2026’s “fragmented but faintly less depressing”. From the vantage point of someone who spends their days studying property data and contributing to the Bank of England’s decision maker panel — in other words, telling Threadneedle Street how the real world actually feels — last year was peak paralysis. Firms sat on their hands waiting for the Autumn Budget as though it were the final episode of a particularly grim straight to streaming digital graveyard boxset.
Late 2026 has delivered the “faint, positive signals” everyone keeps talking about. Translation: some businesses have stopped holding their breath long enough to notice they are still breathing. Recovery is no longer one-size-fits-all; it is more like a badly fitted suit — fine in the North, tight around the middle in the South East, and missing a sleeve entirely in commercial property.
Today at noon, the monetary policy committee will announce whether bank rate remains at 3.75%. Most observers expect another hold; a few hawks still favour 4%, while markets assign a modest chance to a surprise rise. The rest of us will watch with the energy once reserved for penalty shoot-outs.
April 2025’s combination of higher employer NICs and the national living wage was less a cost shock than a structural personality change for SMEs. Consumer-facing firms absorbed a roughly 10% increase in wage bills and discovered that “passing it on to the customer” is a lovely theory until the customer sees the new price and hits the Temu app instead.
The sophisticated mitigation strategies now in play include:
- Natural attrition as a business model. When someone leaves, the role is “reviewed”. The review usually concludes that the remaining staff can simply work a little harder. Headcount scrutiny has become an Olympic sport.
- The automation pivot. Every SME now claims to be “investing in AI”. In practice, this often means buying a chatbot that occasionally hallucinates invoice dates and a cloud subscription nobody fully understands. Cybersecurity spending has risen because everyone fears becoming the next cautionary tale.
- A long margin rebuild. Clients have developed a remarkable ability to reject price increases. Firms have therefore accepted that profitability is now more of a lifestyle choice than a quarterly target.
- Hoarding the useful people. Despite a looser labour market, specialist and technical staff are being treated like rare Pokémon cards. Everyone else remains on the “we’ll see how it goes” list.
All this caution is excellent news if you enjoy empty commercial buildings and estate agents looking wistfully at their phones.
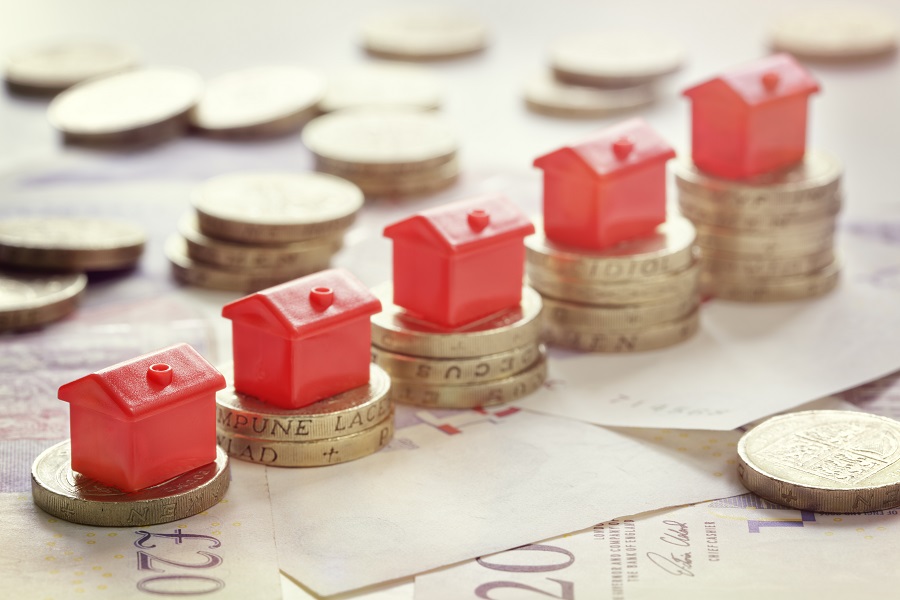
The property market remains the nation’s favourite economic weathervane, currently pointing in several directions at once. We have moved from early-2025 gloom to late-2026 “softening” — estate-agent shorthand for prices doing whatever they like, depending on the postcode.
Sellers are increasingly discovering that the original asking price was more of a conversation starter than a serious offer. Housebuilders, meanwhile, have become experts in bulk sales and “incentives” — a polite way of saying they may throw in the kitchen, and perhaps a small island, to keep cash moving.
The pipeline to property prosperity remains clogged by three familiar villains:
- Regulatory and planning delays. Building Safety Act paperwork has added another layer. Projects that once took months now take “however long it takes, plus another committee”.
- Infrastructure bottlenecks. Waiting for a grid connection has become a national pastime.
- The small-landlord exodus from buy-to-let. Rental inflation remains jaunty while secondary assets sit around looking unloved in a high-rate world.
Today’s rate decision will not magically unclog any of this. It will, however, give everyone something new to argue about over lunch.
In July, the MPC held Bank Rate at 3.75% by six votes to three, with three members preferring a rise to 4%. The justification was classic central-bank poetry: financial conditions were “sufficiently restrictive” to observe how the latest energy shock developed without completely strangling demand.
Energy remains the plot twist nobody requested. Conflict in the Middle East has kept oil and pump prices volatile and higher than anyone would like, while possible second-round effects on wage-setting are what keep MPC members awake at night.
Today, the committee gets to do it all again. A split is highly likely. Some members will favour holding as insurance; a minority will want to raise rates to demonstrate resolve after inflation has remained above target. A hold is still the base case, but the hawks have grown louder as oil prices have pushed up. Either way, the noon announcement will arrive with the usual mixture of gravitas and carefully calibrated vagueness.
For SMEs — and for anyone who owns a building that is not brand new — the state has become the large, well-meaning relative who moved into the spare room “just for a bit”, started using your Wi-Fi, and is now competing with you for the prime slice at the Sunday roast:
- The required return on private-sector investment has risen to “must sparkle more than a fresh gilt”.
- Secondary assets have entered a liquidity trap that attract suspicious side-eye looks by the entire capital market.
- Discretionary capital expenditure still appears in conference speeches, usually in the same tone people use when saying they really must start going to the gym.
In short, the public finances are the awkward auntie: too big to ignore, ruinously expensive to maintain, always finishing the good wine, and capable of souring the mood the moment anyone mentions 2027.
Looking ahead, pay settlements are drifting towards 3.5–3.6%, while the low pay commission is considering another national living wage increase. El Niño, boiling seas, possible US tariffs and whatever the Middle East does next mean inflation is likely to remain twitchy. SME survival in 2027 will depend on ruthless efficiency while everyone pretends the labour market is “looser” and therefore fine.
Today’s decision will not fix the clogged pipeline, the margin squeeze or the fact that secondary commercial assets are still looking for a loving home. It will, however, provide a fresh data point for everyone to overanalyse:
- If rates remain at 3.75%, the “wait and see” crowd can keep waiting.
- If rates rise, a few more SMEs will quietly conclude that Bob’s job really does not need replacing after all.
Stability would be nice. Timely assessments of the inflation outlook would be nicer. Resolving geopolitical uncertainty would be nicest of all.
Until then, property data will keep telling the same story that the decision maker panel has been whispering for months: the recovery is happening — just not everywhere, not evenly, and definitely not to the original timetable.
About the author
 Christian Lister is operations director at X-Press Legal Services, the largest independent provider of conveyancing data across England and Wales. He was appointed to the government’s digital property market steering group (DPMSG) in 2026, helping to shape the delivery of the home buying and selling roadmap. Christian also serves on the executive committee of the council of property search organisations (CoPSO).
This article was submitted by X-Press Legal Service as part of an advertising agreement with Today’s Conveyancer. The views expressed in this article are those of the advertiser and not those of Today’s Conveyancer.