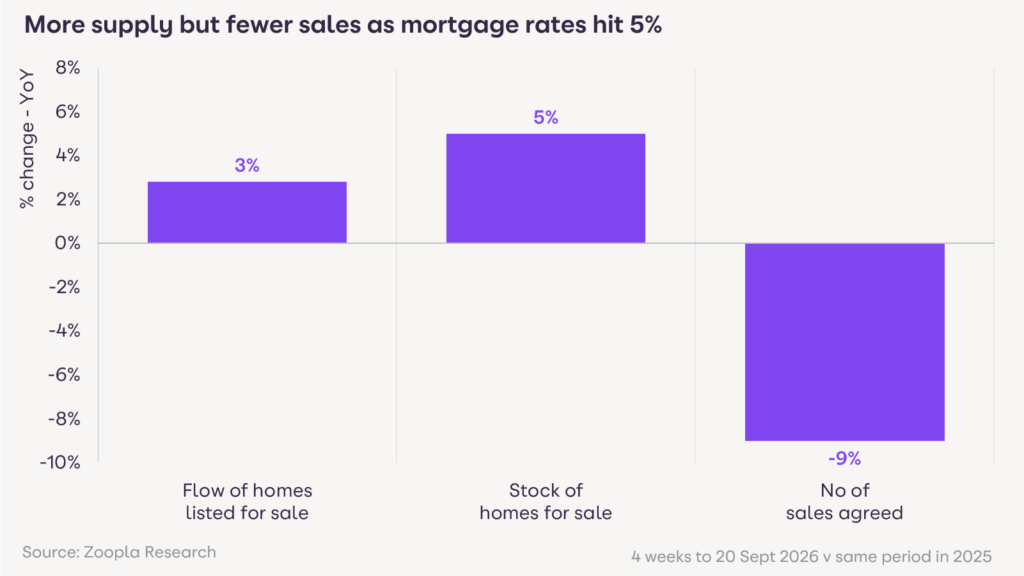
The number of sales agreed has fallen by 9% when compared to the same period 12 months ago according to the latest data from Zoopla.
Comparing market activity data from 18 August to 20 September last year with the same period this year, the property portal said it had also seen a 5% increase in the number of new homes for sale, widening the gap between supply and demand
Weighing in on the debate over the health of the market, the portal said higher buying costs are stalling demand. With average mortgage rates at over 5%, their highest level for three years and up from 4% at the start of the year, the average homebuyer now faces an extra £150 per month (£1,800 a year) in mortgage repayments. As a result every region and country of the UK reports falling sales according to their latest house price index.
Zoopla said it had revised its sales forecasts, expecting house price growth to slow further to around 0.5% by year-end, and 1.1 million transactions in 2026, down from 1.2 million in 2025
Commenting on the latest figure Richard Donnell, Executive Director at Zoopla, said: “The Middle East conflict has pushed up energy prices and mortgage rates, tempering the autumn rebound in housing activity. Borrowing costs are likely to remain elevated, with house price inflation drifting towards 0.5 per cent by year-end and annual sales expected to be closer to 1.1 million versus 1.2 last year. While key measures of housing market activity are lower than last year, there is still plenty of demand for homes. Buyers are simply more cautious and selective about what they view and offer. Sellers who factor in local market conditions and seek detailed advice from their local estate agents on how to set the asking price, can still find a buyer relatively quickly.”
Zoopla also said one quarter of homes newly listed this month have been on the market before, most often flats and larger homes; six in ten of these have been relisted at a lower price.